Quantitative development
Vega: Harnessing Volatility to Optimize Your Options Portfolio
Learn how to leverage vega sensitivity to optimize your options portfolio and implement effective volatility-based trading strategies.
Joaquin Bejar · Engineering notebook
Quantitative development, trading infrastructure and algorithms, explained with code and measurements. Written in English and translated into Spanish, French, German and Simplified Chinese.
Quantitative development
Learn how to leverage vega sensitivity to optimize your options portfolio and implement effective volatility-based trading strategies.
Quantitative development
Exploring why gamma becomes particularly problematic in delta-neutral strategies for same-day expiration options, with practical insights for traders.
Quantitative development
Understanding how theta works and its impact on options strategies, with insights into time decay calculation and its non-linear behavior.
Quantitative development
Exploring mathematical frameworks for delta-neutral options strategies that exploit pricing inefficiencies through systematic quantitative modeling.
Quantitative development
A comprehensive framework for classifying options strategies based on market bias, volatility expectations, and risk tolerance to enhance trading decisions.
Watch an options position breathe.
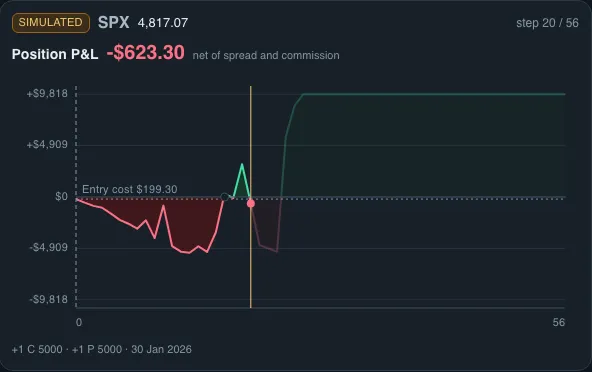
A simulator that walks a multi-leg options position through a stochastic market, step by step, showing the P&L and twelve Greeks as they move. Every price is a bid or an ask, so spread and commission are charged on entry, and every run is reproducible and shareable.
Order books & matching
A high-performance, thread-safe limit order book implementation written in Rust. This project provides a comprehensive order matching engine designed for low-latency trading systems, with a focus on concurrent access patterns and lock-free data structures.
Options & derivatives
OptionStratLib is a comprehensive Rust library for options trading and strategy development across multiple asset classes.
Market making & DeFi
A Rust library implementing quantitative market making strategies, starting with the Avellaneda-Stoikov model. This library provides the mathematical foundations and domain models necessary for building automated market making systems for financial markets.